Chase Freedom Unlimited: How Does Its Cashback Program Work?

Navigating the world of credit card rewards can often feel like trying to solve a complex puzzle. With so many terms, percentages, and fine print details floating around, finding a financial tool that offers both simplicity and high-value returns is a top priority for smart consumers. Among the heavy hitters in the personal finance space, the Chase Freedom Unlimited has consistently remained a fan-favorite card. But what makes it tick, and more importantly, how does its cashback program actually work behind the scenes?
Understanding the mechanics of your rewards earning potential is the first step toward maximizing every single dollar you spend. Whether you are buying groceries, booking a long-awaited family vacation, or grabbing your morning coffee, this card handles rewards through a structured tiered system that rewards both everyday habits and specific lifestyle choices. Let us dive deep into the architecture of the Chase Freedom Unlimited cashback program, breaking down everything from earning multipliers and redemption choices to advanced strategies that can supercharge your wallet.
Demystifying the Core Earning Structure: Flat-Rate vs. Bonus Categories
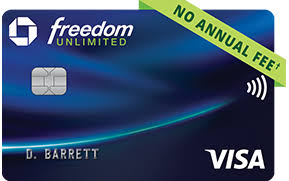
At its core, the Chase Freedom Unlimited is celebrated for striking a rare balance between a flat-rate rewards card and a targeted bonus card. Many traditional cash-back cards either offer a flat percentage on everything—ignoring where you spend extra money—or focus heavily on rotating categories that require constant activation and tracking. The Chase Freedom Unlimited bridges this gap by offering a solid foundation complemented by robust bonus multipliers.
The earning framework rests upon four primary tiers:
- 5% Cash Back on Travel:Any travel purchased through the Chase Travel portal earns an impressive 5% back. This includes flights, hotels, car rentals, and excursions booked directly through their ecosystem.
- 3% Cash Back on Dining: Food lovers rejoice. You earn 3% back on dining at restaurants, which comprehensively covers traditional dine-in experiences, takeout orders, and eligible delivery services.
- 3% Cash Back at Drugstores: Prescription refills, over-the-counter medications, and everyday items bought at eligible drugstores also pull in a 3% return.
- 1.5% Cash Back on Everything Else: This is the ultimate safety net and the card’s signature feature. Every single purchase that does not fall into the specific bonus categories automatically earns an unlimited 1.5% cash back.
Many beginner cardholders underestimate the power of a 1.5% baseline. While many standard entry-level cards stick strictly to a 1% return on general purchases, getting 1.5% back on utility bills, insurance payments, clothing, and unexpected expenses adds up significantly over the course of a year.
How Chase Ultimate Rewards Points Power Your Cashback
One detail that frequently confuses new cardholders is how Chase tracks and displays rewards.Even though it is widely marketed as a “cashback” credit card, the earnings are actually tracked in the form of Chase Ultimate Rewards points.
Do not let this terminology intimidate you. The math behind it is wonderfully straightforward: 1 Ultimate Rewards point is equal to 1 cent in cash value.
Therefore, if your statement summary shows that you have earned 10,000 points, you possess exactly $100 worth of cash back. This point-based tracking system operates quietly in the background, but it acts as a massive hidden advantage. Because your rewards accumulate as Ultimate Rewards points rather than a simple digital ledger balance, they open the door to advanced travel hacking strategies later on if you decide to expand your card portfolio. Best of all, these points do not expire as long as your account remains open and in good standing, meaning you can stockpile them for a major financial goal or cash them out whenever you see fit.
Exploring Flexible Redemption Options for Everyday Users
When the time comes to finally reap the fruits of your spending labor, Chase provides multiple pathways to access your rewards. You are never locked into a single rigid redemption method, giving you full control over how your money flows back to you.
The primary redemption avenues include:
- Statement Credits: You can apply your points directly toward your current card balance, effectively wiping out a portion or all of your monthly bill.
- Direct Deposit:If you prefer cash in hand, you can have your rewards directly deposited into a checking or savings account (typically requiring a U.S. bank account).There is no minimum redemption threshold for cash back, meaning you can cash out even if you only have a few dollars accumulated.
- Gift Cards:Chase allows you to redeem points for gift cards from popular retailers, restaurants, and entertainment venues. Occasionally, Chase runs promotions where specific brand gift cards are discounted, giving your points slightly more purchasing power.
- Shopping at Major Retailers:You can link your credit card account to partner platforms like Amazon, allowing you to use your points directly at checkout to pay for purchases.
- Booking Travel:You can use your accumulated points to pay for flights, hotels, or rental cars directly through the Chase Travel portal at a rate of 1 cent per point.
For the average consumer who just wants a simple, no-fuss experience, requesting a direct deposit or statement credit provides a clean, reliable way to turn everyday spending into tangible financial savings.
Unlocking Hidden Value: The Power of the “Chase Trifecta”
If you talk to seasoned personal finance enthusiasts or advanced credit card rewards hobbyists, they will tell you that the true power of the Chase Freedom Unlimited goes far beyond its standalone features. While earning 1.5% on general purchases is great on its own, it transforms into an elite-tier earning engine when combined with an annual fee-bearing premium card, such as the Chase Sapphire Preferred or the Chase Sapphire Reserve.
This synergy is popularly known in the credit card community as the Chase Trifecta. Here is how the magic happens behind the scenes:
When you hold the Chase Freedom Unlimited as a standalone card, your points are worth 1 cent each. However, if you also hold a card like the Chase Sapphire Preferred, Chase permits you to move your Ultimate Rewards points freely and instantly between your credit card accounts at a 1:1 ratio.
Once your Freedom Unlimited points are transferred over to your Sapphire account, their value changes dramatically:
- Increased Travel Portal Value: Your points become worth 25% to 50% more when redeemed for travel through the Chase portal depending on your Sapphire tier.
- Transfer Partners:You can transfer those points directly to airline and hotel loyalty programs (such as United MileagePlus, World of Hyatt, or Southwest Rapid Rewards), where expert travelers frequently squeeze out 2 cents or much more per point in value.
Because of this mechanism, many savvy consumers use a premium travel card for dining and travel, but use the Chase Freedom Unlimited as their everyday “catch-all” card for miscellaneous bills, ensuring that every dollar spent earns a minimum of 1.5 valuable points that can later be funneled into luxury hotel stays or free flights.
Analyzing Cardholder Perks, Sign-Up Bonuses, and Additional Protections
Beyond the base mechanics of earning and redeeming points, a comprehensive look at the program must account for the auxiliary benefits and promotional offers attached to the account. These features heavily influence the overall value proposition of keeping the card in your wallet long-term.
The Welcome Offer
To kickstart your rewards journey, Chase typically structures a generous initial sign-up bonus for new cardmembers. Usually, this involves earning a substantial cash bonus after meeting a designated minimum spending requirement within the first few months of account opening. Meeting this threshold through normal, organic budgeting can instantly yield a high-value return that dwarfs what you would earn from standard spending alone during your first year.
Zero Annual Fee
One of the most appealing aspects of the Chase Freedom Unlimited is its $0 annual fee. Many high-earning rewards cards demand steep yearly membership costs just to keep the account active, which can eat heavily into your net cash back if you do not spend heavily. Because the Freedom Unlimited costs nothing to hold year after year, every single dollar of cashback you earn is pure profit.
Built-In Shopping and Travel Protections
You might not immediately associate a cash-back card with insurance or consumer protection, but Chase packs several valuable safety nets into this zero-fee product:
- Purchase Protection:Covers eligible new purchases against damage or theft for a specified window following the purchase date.
- Extended Warranty Protection:Adds an additional year to eligible manufacturer warranties.
- Trip Cancellation and Interruption Insurance:Reimburses you for pre-paid, non-refundable passenger fares if a covered trip is interrupted or canceled due to severe weather, sickness, or other qualifying emergencies.
Potential Pitfalls to Watch Out For: Fees and Rates
While the program features an array of impressive financial advantages, maintaining a healthy relationship with any credit card requires a clear-eyed look at potential costs. Smart financial management means enjoying the rewards while completely avoiding the traps.
- Foreign Transaction Fees: The card carries a foreign transaction fee on purchases made outside the United States or processed through foreign merchants. If you plan on traveling internationally or shopping frequently on overseas websites, this fee can quickly outweigh the cashback you earn. Travelers often pair this card with a zero-foreign-transaction-fee alternative when venturing abroad.
- Variable APR: Like most revolving credit lines, carrying a balance from month to month will subject you to a variable Annual Percentage Rate (APR). The interest charges accrued by carrying a balance will quickly erase any cashback rewards you accumulate. To truly win at the credit card rewards game, you must treat the card like a debit tool, paying off your statement balance in full every single month.
Step-by-Step Guide: How to Maximize Your Earnings Every Month
If you want to transition from a casual cardholder into a master of cash-back optimization, adopting a structured routine helps ensure you never leave money on the table. Consider implementing this simple optimization workflow:
- Audit Your Monthly Budget: Review your bank statements to see where your money actually goes. Identify your heavy spending sectors, such as dining out, grocery delivery, rideshares, and recurring utility bills.
- Assign the Right Card to the Right Task: Use your Chase Freedom Unlimited whenever you dine out at restaurants, order delivery, buy items at a drugstore, book travel through the portal, or pay for miscellaneous general expenses that do not trigger higher multipliers elsewhere.
- Track Your Sign-Up Bonus Window: If you are a new cardholder, map out your upcoming major purchases to easily clear the initial spend requirement within the first three months without overspending or buying things you do not need.
- Monitor Your Points Balance:Log into your online dashboard or mobile app regularly to watch your Ultimate Rewards points accumulate. Decide whether you want a periodic cash payout to lower your monthly expenses or if you are saving points for a larger financial milestone.
- Practice Responsible Habits: Always set up autopay for the full statement balance. Protecting your credit score and avoiding interest charges will always yield a higher return than any cashback percentage can offer.
Is the Chase Freedom Unlimited Right for You?
The Chase Freedom Unlimited stands out as a masterclass in credit card program design. By combining a reliable 1.5% baseline floor with lucrative 3% and 5% multipliers on everyday essentials like dining, drugstores, and travel, it eliminates the cognitive fatigue of rotating categories while still delivering exceptional returns.
When you factor in the $0 annual fee, the lucrative welcome offer, robust consumer protections, and the ultimate flexibility of cashing out or scaling up points through the Chase Ultimate Rewards ecosystem, it easily earns its reputation as a staple financial tool. Whether you are taking your very first steps into the world of rewards credit cards or looking for a reliable, high-performing catch-all card to anchor your wallet, understanding how the program works allows you to turn ordinary, everyday spending into an automated engine of financial return.