Apple Card: How Does Daily Cash Work?

Navigating the world of credit card rewards can often feel like trying to decipher a foreign language. Traditional credit cards typically force you to accumulate confusing points or miles, track complicated quarterly bonus categories, and wait until the end of a billing cycle—or even until you reach a high minimum threshold—just to redeem what you have earned. Furthermore, these rewards often come with expiration dates or hidden devaluation rules that make maximizing your earnings an exhausting chore.
Enter the Apple Card and its signature reward system known as Daily Cash.Designed to strip away the traditional complexities of plastic credit cards, Daily Cash offers a refreshing, straightforward approach to getting money back on everyday purchases. But how does the system actually function behind the scenes? Understanding the mechanics, percentages, and redemption paths can help you decide whether this financial tool fits neatly into your wallet and spending habits.
Understanding the Basics of Daily Cash Mechanics
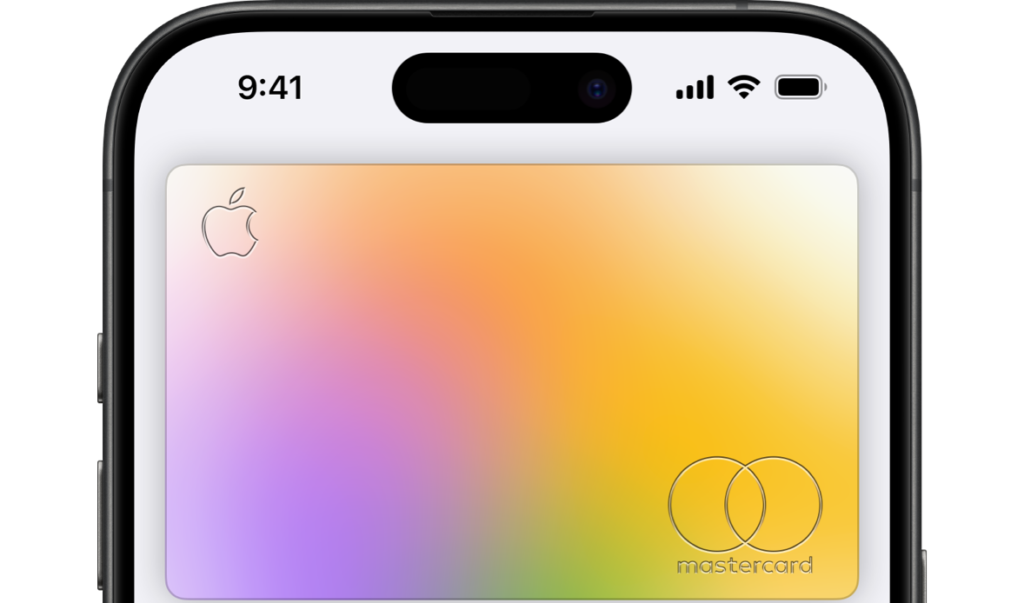
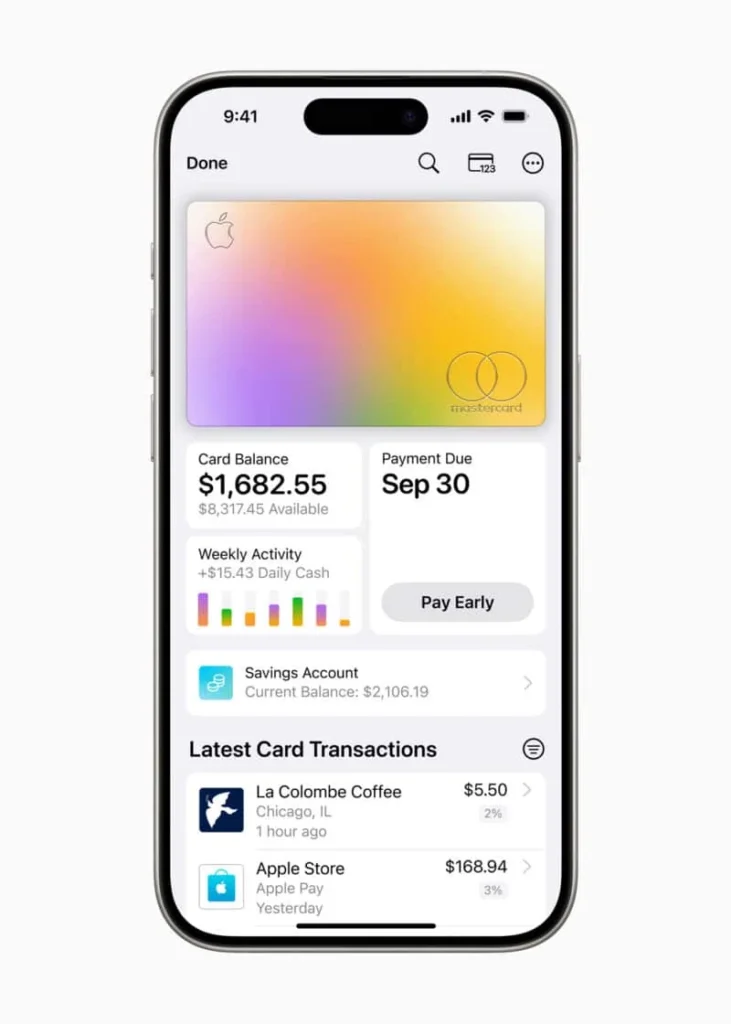
At its core, Daily Cash is a cash-back reward program tied directly to your credit card usage, but with a unique twist regarding payout speed. Unlike traditional cards that calculate your earnings once a month and credit them on your billing statement, Daily Cash is distributed almost as soon as your transactions settle.
When you make a purchase using your card, a specific percentage of the total amount spent is immediately calculated and returned to you. Because the system integrates deeply with the digital wallet ecosystem on your smartphone, tracking your earnings requires nothing more than a few taps on your screen. There are no complicated formulas to memorize, no tiers to unlock through complex spending traps, and absolute transparency regarding every single transaction you make.
The money you receive is actual cash, not arbitrary points.This means it never loses value, never expires, and carries no strings attached. Whether you spend pocket change on your morning coffee or make a major investment in household electronics, the reward mechanism operates with the exact same level of consistency.
Breaking Down the Reward Tiers: 3%, 2%, and 1%
The structure of Daily Cash relies on a simple, tiered percentage system based entirely on how and where you complete your transaction. Remembering how these tiers work is remarkably easy because they follow a descending scale that rewards digital and ecosystem-specific payments above traditional card swipes.
- The 3% Tier:You earn three percent back on everything you buy directly from Apple, including hardware, software applications, digital subscriptions, and services. Additionally, this top-tier reward rate applies when you use your card via digital checkout with select retail partners—such as major pharmacies, select transit networks, and designated corporate partners—provided you complete the transaction using digital wallet technology.
- The 2% Tier: This is the rate you receive on the vast majority of your everyday spending, provided you use your digital wallet at checkout. Whenever you tap your phone or watch at grocery stores, restaurants, gas stations, or online merchants that accept digital contactless payments, you secure two percent back on the transaction.
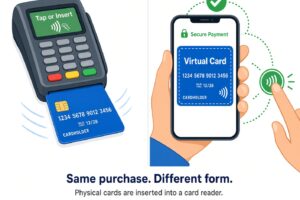
- The 1% Tier:This baseline percentage applies whenever you use the physical titanium card or type your virtual card number into a traditional online merchant website that does not support modern digital wallet checkouts. Because digital contactless payments are so widespread, you will ideally use this physical option less frequently, but it ensures you still earn something even where advanced technology isn’t accepted.
Where Does Your Money Go? Exploring Redemption Options
One of the most appealing aspects of Daily Cash is the flexibility of choice regarding where your earned funds land once they are paid out. Users are not locked into a single ecosystem endpoint; instead, you can configure your preferences directly inside your mobile device settings to route the money according to your personal financial goals.
The first destination option is a dedicated digital cash balance account. When routed here, your rewards accumulate instantly and can be used immediately to buy items anywhere contactless payment is accepted, sent directly to friends and family as peer-to-peer payments, or transferred to an external bank account.
The second primary destination option is a high-yield savings account linked to the card. By choosing this path, every cent of Daily Cash you earn is automatically diverted into a secure savings vehicle that accrues interest over time. This creates a completely hands-off compounding mechanism where your routine daily spending quietly builds an emergency fund in the background without requiring manual transfers or active budgeting decisions.
Maximizing Your Earnings Without Changing Your Lifestyle
Optimizing a credit card reward program usually requires altering how you live, but Daily Cash rewards strategic alignment rather than excessive spending. Because the reward percentages scale heavily based on payment method rather than merchant categories that shift every month, maximizing your return is straightforward.
The golden rule for maximizing your cash back is prioritizing digital contactless payments over physical card swipes whenever possible. Since the difference between using the physical card and tapping your phone is a full percentage point on standard purchases, ensuring that your digital wallet is set as your default payment method on your phone makes a substantial cumulative difference over the course of a year.
Furthermore, routing your routine household bills, digital entertainment subscriptions, and occasional technology upgrades through the platform locks in the maximum reward tier automatically. Because there are no annual fees associated with the account, every percentage point earned represents pure, unmitigated gain rather than an offset against a yearly membership cost.
Comparing Daily Cash to Traditional Credit Card Points
To truly appreciate how Daily Cash functions, it helps to contrast it with the traditional points and miles model used by standard rewards credit cards. Traditional cards often lure applicants with massive initial sign-up bonuses, but they typically bury the ongoing rewards in convoluted rules, blackout dates, and frustrating redemption portals.
When you earn points with a standard travel card, the value of those points fluctuates wildly depending on whether you redeem them for statement credits, gift cards, or airline bookings. A point might be worth one cent in one category, half a cent in another, or two cents if you manage to hit a rare sweet spot in an airline transfer partner program. This forces consumers to spend excessive time researching reward charts just to ensure they aren’t losing value.
Daily Cash eliminates this mental fatigue entirely. A dollar of Daily Cash is always worth exactly one dollar. There are no restrictions on airlines, no capacity controls on hotel rooms, and no minimum redemption thresholds that force you to leave money sitting on the table. The friction is entirely removed from the reward experience, turning cash-back acquisition into a passive, transparent process.
Common Misconceptions and Fine Print to Keep in Mind
While the mechanics of Daily Cash are exceptionally user-friendly, a few common misunderstandings can trip up new cardholders if they aren’t paying close attention to the fine print. Clearing up these misconceptions ensures you have realistic expectations about how the reward ledger updates.
A frequent point of confusion involves the exact timing of the payout. While the system is marketed as daily, the cash is technically deposited only after a transaction fully posts and settles with the merchant. While online purchases and major retail transactions usually settle within a day or two, pending charges will not reflect their cash rewards until the merchant clears the charge through the payment network.
Another important detail involves returns and refunds. If you buy an item and later decide to return it to the store for a full refund, the Daily Cash you earned on that specific purchase will be charged back and deducted from your balance.If you have already spent or transferred those funds, the deduction will adjust your available balance accordingly, ensuring that rewards are only distributed for finalized, non-returned retail transactions.
Additionally, understanding how the program handles shared accounts is vital for households. If you manage an account with a co-owner or family participants, each individual earns their own Daily Cash based on their personal card usage. However, the destination rules and account management permissions vary slightly between primary owners and younger participants, meaning everyone should configure their preferred payout settings individually within their own device interfaces.
Final Thoughts on Streamlining Your Financial Rewards
The evolution of credit card rewards has long favored banks and complex institutional structures that profit when consumers fail to track their points. Daily Cash cuts through this noise by offering a model rooted in radical transparency, immediate gratification, and absolute simplicity.
By delivering real currency directly into your hands on a rolling daily basis, the system transforms routine spending into an effortless accumulation of wealth. Whether you choose to spend your earnings immediately on everyday essentials or funnel them into a high-yield savings vehicle to watch them grow over time, the power remains entirely in your hands. Understanding these core mechanics allows you to make informed financial decisions, optimize your everyday purchasing power, and enjoy a reward structure that finally works for you rather than against you.