What Is a Ponzi Scheme and How Can You Spot One?

Promises of fast, effortless, and guaranteed wealth have lured everyday investors into financial traps for more than a century. While markets rise and fall unpredictably, fraudulent operators exploit human hope and fear of missing out to build illusions of steady profit. Understanding how these frauds operate is the single best defense for protecting your hard-earned savings.
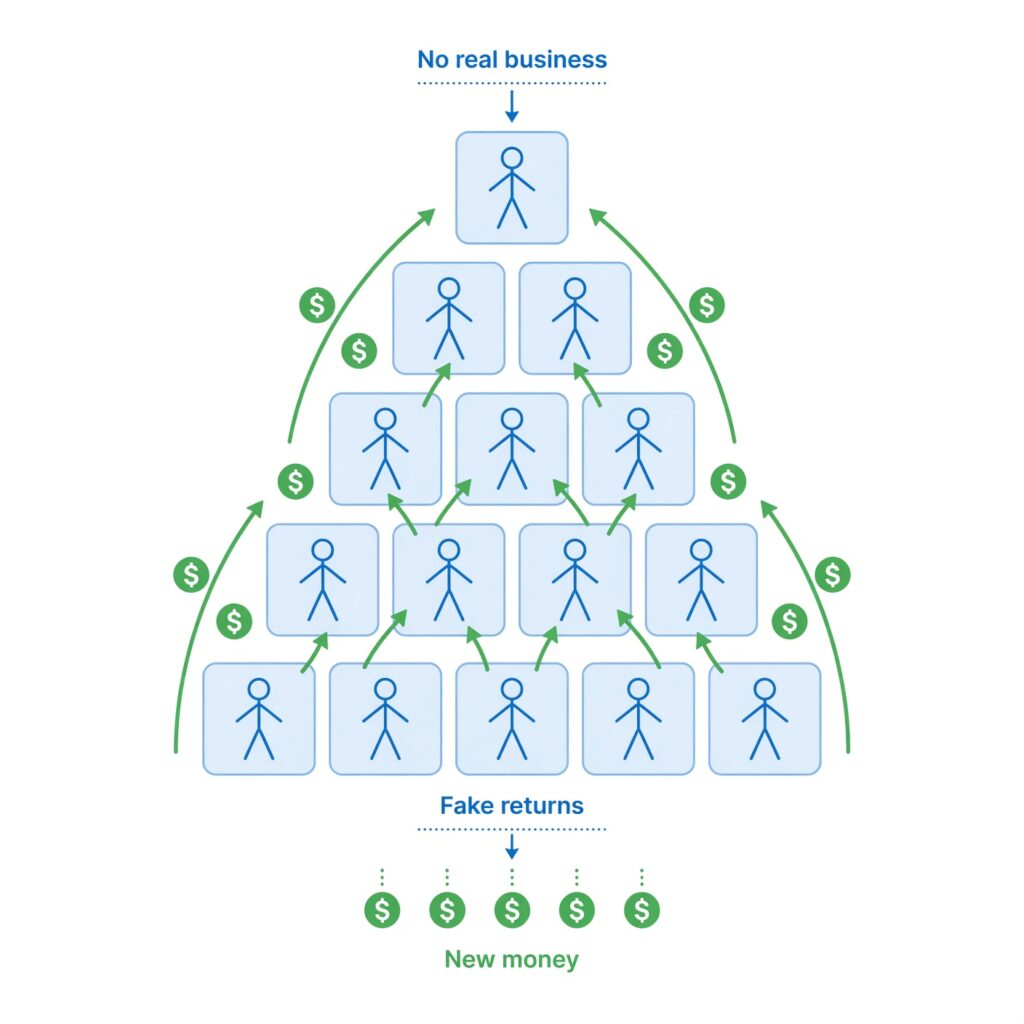
A Ponzi scheme is an investment fraud that pays existing investors with funds collected from new investors rather than from legitimate business profits. Organizers often promise high returns with little or no risk, recruiting a constant stream of new participants to keep the illusion alive until the money dries up and the entire operation collapses.
Whether you are evaluating a new stock opportunity, a private real estate fund, or a cutting-edge cryptocurrency platform, knowing the mechanics and warning signs of this classic scam can save you from devastating financial loss. Below is a complete breakdown of how these schemes work, how to spot them before investing a dime, and what steps to take if you suspect fraud.
How Does a Ponzi Scheme Actually Work?
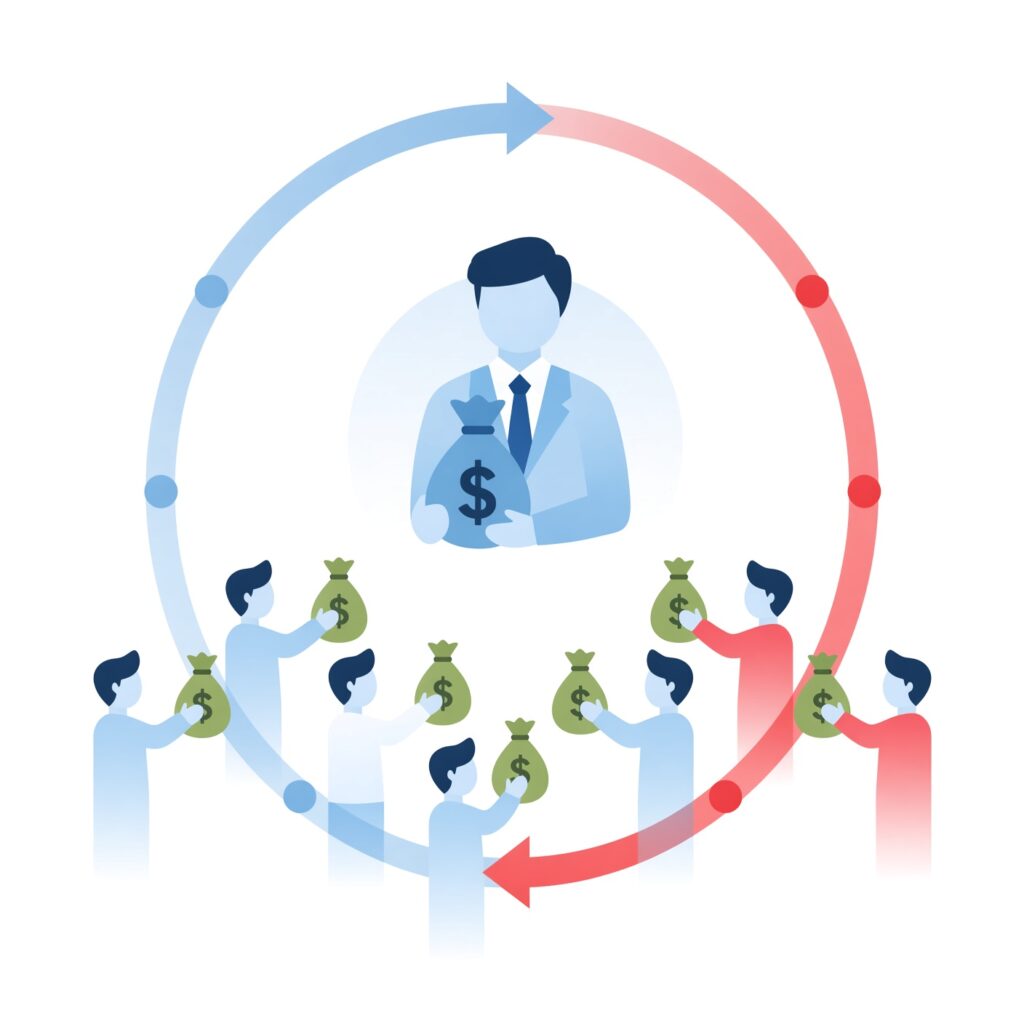
At its core, a Ponzi scheme is a simple shell game disguised behind complex financial jargon. Instead of investing your money into productive assets—such as profitable companies, real estate, or commodities—the schemer deposits your cash into a central pool and uses it to pay off earlier participants.
To make the operation look legitimate, the promoter issues fabricated account statements showing steady, impressive gains. Seeing these numbers grow on paper builds trust. Satisfied early investors often reinvest their supposed profits and enthusiastically recommend the opportunity to friends, family members, and coworkers.
This cycle creates a mathematical trap. Because no real wealth is being generated, the operator needs an exponentially growing number of new investors just to pay the promised returns to existing ones. Eventually, one of three things happens:
- Recruitment slows down: The operator runs out of new people willing to hand over cash.
- Withdrawals spike: An economic downturn or market panic prompts too many investors to ask for their principal back at the same time.
- Regulators intervene: Authorities uncover accounting irregularities or respond to whistleblower complaints.
When any of these triggers occur, the cash flow halts immediately. The scheme collapses overnight, leaving the vast majority of participants with empty accounts and broken promises.
Where Did the Term Ponzi Scheme Come From?
Although the tactic of robbing Peter to pay Paul has existed for centuries, the fraud takes its name from Charles Ponzi, an Italian immigrant who orchestrated a massive scam in Boston between 1919 and 1920.
Ponzi claimed he could generate enormous profits by exploiting currency exchange rates through international reply coupons—vouchers used to prepay postage across borders. He promised investors a 50% return in just 45 days, or 100% in 90 days. Word spread rapidly across New England, and tens of thousands of people poured roughly $20 million into his company (an amount worth hundreds of millions in today’s dollars).
In reality, buying and redeeming millions of postage coupons was logistically impossible. Ponzi was simply taking money from new arrivals to pay early backers. When investigative journalists at The Boston Post exposed the mathematical impossibility of his business model in August 1920, his empire crumbled within days, landing him in federal prison.
Ponzi Scheme vs. Pyramid Scheme: Key Differences Explained
People frequently confuse Ponzi schemes with pyramid schemes because both rely on a continuous influx of new money to survive. However, they operate differently in structure and how participants are recruited.
| Feature | Ponzi Scheme | Pyramid Scheme |
|---|---|---|
| How Money Is Made | Investors hand money to a central manager who claims to invest it on their behalf. | Participants pay an upfront fee and earn money primarily by recruiting other members. |
| Investor Involvement | Passive. Investors believe a financial expert is actively trading or managing assets. | Active. Members must constantly pitch and sign up new recruits to move up tiers. |
| Awareness of Structure | Victims usually have no idea their payouts come from newer investors. | Participants know they must recruit others, though they are misled about profitability. |
| Primary Hook | Guaranteed high returns with little to no market risk. | Turning a small upfront buy-in into massive wealth through downline commissions. |
Understanding this distinction helps you evaluate different pitches. If someone asks you to hand over money so they can trade for you quietly in the background, watch out for a Ponzi setup. If someone pressures you to pay for a starter kit and recruit three friends who each recruit three more, you are looking at a pyramid structure.
7 Major Red Flags to Spot a Ponzi Scheme Early
Fraudsters continually adapt their pitches to match current financial trends, shifting from postage coupons to hedge funds, green energy, and decentralized finance. Despite the changing packaging, almost every Ponzi scheme exhibits the same core warning signs.
1. High Investment Returns With Little or No Risk
In legitimate financial markets, risk and reward are permanently linked. To achieve higher returns, an investor must accept greater volatility and the genuine possibility of losing money. When a promoter promises double-digit annual returns while claiming your principal is completely safe or guaranteed, you are looking at a classic scam.
2. Overly Consistent Returns Regardless of Market Conditions
Real investments fluctuate. Even the best hedge funds and blue-chip stocks experience losing quarters, bear markets, and periods of flat growth. If an investment produces steady, positive returns month after month—even when the broader stock market is crashing—those numbers are almost certainly fabricated.
3. Unregistered Investments and Unlicensed Sellers
Federal and state securities laws require most investment offerings to be registered with regulatory bodies such as the Securities and Exchange Commission (SEC), and sellers must hold valid licenses. Fraudsters frequently avoid registration because the disclosure process would expose their lack of real assets. Always verify both the investment and the person selling it through official regulatory databases before transferring money.
4. Secretive or Overly Complex Strategies
Con artists love using impenetrable jargon—such as “proprietary algorithmic arbitrage” or “exclusive off-market prime bank instruments”—to intimidate investors into silence. If the person pitching the investment cannot explain clearly in plain English how the business generates cash flow, walk away. Never put money into something you do not understand.
5. Issues With Paperwork and Account Statements
Legitimate financial institutions provide clear, timely, and independently audited statements showing exact holdings, transaction dates, and fees. Ponzi operators often deliver vague summaries, make frequent excuses for clerical errors, or fail to provide documentation showing where assets are held by a recognized third-party custodian.
6. Difficulty Receiving Payments or Pressure to Roll Over Funds
A major warning sign occurs when you try to cash out your principal or profits. If the fund manager delays your withdrawal, invents sudden administrative hurdles, or aggressively pushes you to “roll over” your gains into a new high-yield tier, the scheme is likely running out of cash.
7. Affinity Fraud and Social Pressure
Many schemes spread inside tight-knit communities—such as religious congregations, retiree clubs, alumni networks, or professional associations. Fraudsters exploit shared trust and cultural bonds so victims lower their guard and skip independent due diligence.
Famous Historical and Modern Ponzi Schemes
Looking at real-world cases reveals how convincing these operations can appear on the surface—and how devastating the fallout becomes when they unravel.
Bernie Madoff’s Wall Street Deception
Bernard Madoff orchestrated the largest financial fraud in history, defrauding thousands of individuals, charities, and pension funds out of an estimated $64.8 billion in paper wealth (with roughly $17.5 billion in actual principal lost). A respected former chairman of NASDAQ, Madoff claimed to use a “split-strike conversion” options strategy that delivered steady 10% to 12% annual returns year after year.
In truth, Madoff never executed a single trade for his advisory clients for decades. He simply deposited client checks into a single JPMorgan Chase bank account and used those funds to honor redemption requests. When the 2008 financial crisis triggered $7 billion in withdrawal requests, the account ran dry, and Madoff confessed to his sons.
Allen Stanford and the Antigua Banking Scam
Texas financier Allen Stanford ran a $7 billion Ponzi scheme through his Antigua-based Stanford International Bank. He sold bogus certificates of deposit (CDs) that promised significantly higher interest rates than traditional U.S. banks, claiming the funds were safely invested in liquid, blue-chip global securities. Instead, Stanford diverted billions to fund personal luxuries, real estate ventures, and lavish sports sponsorships before federal agents shut down his empire in 2009.
Crypto and Digital Asset Ponzi Schemes
Modern scammers have adapted the Ponzi playbook for the digital age. Platforms like BitConnect and OneCoin promised astronomical daily returns through automated crypto-trading bots or revolutionary new blockchain tokens. By combining complex technical buzzwords with aggressive social media marketing, these platforms drained billions of dollars from retail investors worldwide before collapsing.
How to Protect Your Money Before Investing
Protecting yourself does not require a finance degree—it requires discipline and a few simple verification habits before you ever sign a check or initiate a wire transfer.
- Verify registration independently: Use free official tools like FINRA’s BrokerCheck or the SEC’s Investment Adviser Public Disclosure (IAPD) website to confirm that the advisor and firm are properly licensed and have no disciplinary history.
- Check for independent custody: Ensure your funds are held by a reputable, independent third-party custodian—not directly by the fund manager or an affiliated entity they control.
- Demand audited financial statements: Legitimate private funds are audited annually by recognized, independent accounting firms. Verify the auditor’s name and confirm they actually work with the fund.
- Take your time: Legitimate opportunities do not expire in 24 hours. High-pressure sales tactics designed to rush your decision are a hallmark of financial fraud.
- Consult a trusted, independent professional: Run any private or unfamiliar investment pitch past an independent Certified Public Accountant (CPA) or fee-only Certified Financial Planner (CFP) who receives no commission from the deal.
What to Do If You Suspect a Ponzi Scheme
If you realize you have invested in a suspected Ponzi scheme—or someone is actively pitching one to you—acting quickly can help limit your losses and assist authorities in stopping the fraud.
- Stop sending money immediately: Do not invest additional funds, and ignore promises that paying a “tax,” “release fee,” or “administrative charge” will unlock your frozen account.
- Request a full withdrawal quietly: If the scheme has not yet collapsed publicly, submit a standard request to withdraw your principal without tipping off the operator that you suspect fraud.
- Preserve all documentation: Save every email, text message, contract, wire receipt, marketing brochure, and account statement. These records are critical for law enforcement and asset recovery efforts.
- Report the fraud to authorities: File complaints immediately with the Securities and Exchange Commission (SEC), the Commodity Futures Trading Commission (CFTC), the FBI’s Internet Crime Complaint Center (IC3), and your state securities regulator.
- Watch out for recovery scams: Victims of financial fraud are frequently targeted a second time by scammers posing as government agents or specialized lawyers who claim they can recover your lost money for an upfront fee. Never pay upfront fees to recover scam losses.
Frequently Asked Questions About Ponzi Schemes
Can investors ever get their money back from a Ponzi scheme?
In some cases, victims recover a portion of their principal through court-appointed receivers or bankruptcy trustees. These officials seize remaining assets owned by the fraudster and pursue “clawback” lawsuits against early investors who withdrew more money than they originally put in, redistributing those funds fairly among net losers. However, full recovery is rare and often takes years.
Are Ponzi schemes always illegal?
Yes. Operating a Ponzi scheme violates federal and state securities laws, wire fraud statutes, and anti-fraud regulations. Perpetrators face severe criminal penalties, including decades in federal prison, alongside civil lawsuits and asset forfeiture.
Why do smart, wealthy people fall for Ponzi schemes?
Fraudsters use psychological triggers like exclusivity, social proof, and fear of missing out. When investors see respected peers or community leaders receiving steady payouts, they often rely on social trust rather than independent verification—proving that emotional discipline matters just as much as financial knowledge.
Staying safe in today’s financial landscape comes down to healthy skepticism. Whenever an opportunity sounds too smooth, too secret, or too profitable to be true, step back, verify the facts independently, and keep your money anchored in transparent, regulated investments.