How to Improve Your Chances of Getting a Loan

Getting approved for a loan can sometimes feel like a daunting puzzle. Whether you are planning to buy your first home, purchase a reliable car, consolidate high-interest credit card debt, or cover an unexpected medical expense, having a lender say “yes” makes all the difference. However, lenders do not just hand out money blindly. They look closely at your financial background to measure how likely you are to pay them back on time.
If you have ever faced a loan denial, you know how frustrating it can be. The good news is that securing a loan is not a matter of luck. It is a predictable process built on clear financial habits, preparation, and strategy. By understanding what lenders look for and taking proactive steps to strengthen your profile, you can dramatically improve your chances of getting approved—often while securing a lower interest rate that saves you thousands of dollars over the life of the loan.
1. Understand How Lenders Evaluate Your Credit Score
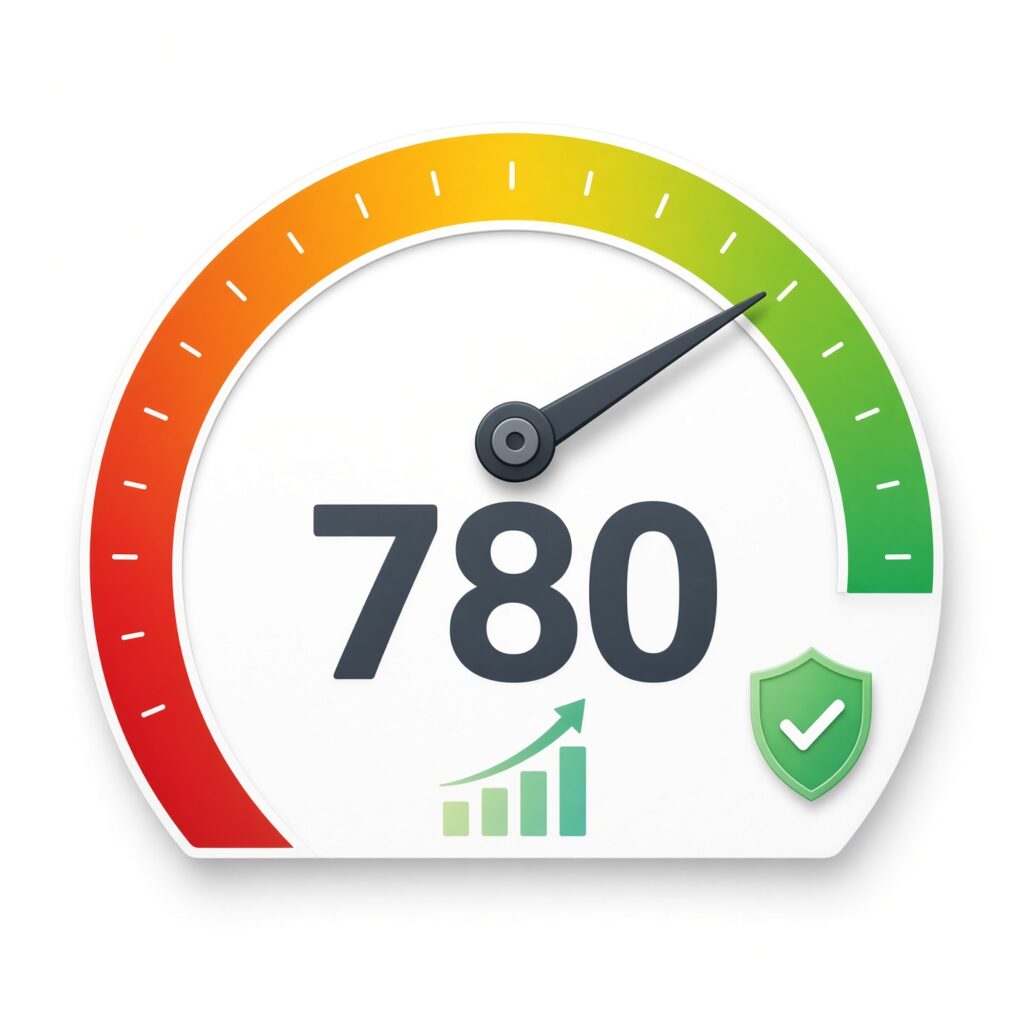
Your credit score is often the very first thing a lender looks at when reviewing your application. Think of your credit score as a financial resume or a digital report card that tells banks and credit unions how trustworthy you are with borrowed money. In the United States, credit scores generally range from 300 to 850, calculated primarily by major bureaus like Equifax, Experian, and TransUnion.
Lenders use this three-digit number to determine your interest rate and whether they want to take the risk of lending to you at all. A higher score tells the lender that you pay your bills on time and manage your debts responsibly. A lower score suggests that you might be a high-risk borrower, which can lead to higher interest rates, stricter conditions, or a flat-out rejection.
To improve your score before applying for a loan, start by reviewing your credit report for errors. Mistakes on credit reports are surprisingly common, and disputing them can sometimes boost your score quickly. Additionally, focus on making every single payment on time. Payment history makes up the largest chunk of your credit score, so consistency is key. Keep your credit utilization low—meaning you should try to use only a small percentage of your available credit limits at any given time—and avoid closing your oldest credit card accounts, as a longer credit history works in your favor.
2. Master Your Debt-to-Income (DTI) Ratio
While your credit score shows how well you handle credit history, your debt-to-income (DTI) ratio shows your current financial bandwidth. Lenders want to make sure that you are not already stretched too thin. Your DTI ratio compares your total monthly debt payments (such as rent, mortgage, student loans, car payments, and minimum credit card payments) to your gross monthly income.
For example, if you make 5,000 dollars a month before taxes, and your total monthly debt obligations equal 2,000 dollars, your DTI ratio is 40 percent. Most traditional lenders prefer to see a DTI ratio below 36 percent, though some loan programs may accept ratios up to 43 percent or higher depending on your credit score and down payment size.
If your DTI is too high, lenders will worry that an unexpected emergency could make it impossible for you to make your monthly loan payment. To improve your DTI ratio before applying for a loan, you have two primary options: increase your income or decrease your existing debt. While increasing your income through a side hustle or raise takes time, paying down smaller debts or aggressively knocking out credit card balances can lower your monthly obligations and improve your DTI ratio much faster.
3. Gather and Organize Your Financial Documentation
When you apply for a loan, you are asking a financial institution to trust you with their capital. Naturally, they will require proof that you are who you say you are and that your financial claims are accurate. Being disorganized during the application process can delay your approval or give the lender a bad impression.
To make the process smooth and demonstrate professionalism, gather your documents well in advance. Lenders typically require:
- Proof of Identity: A government-issued photo ID, such as a driver’s license or U.S. passport, along with your Social Security number.
- Proof of Income: Recent pay stubs covering the last 30 to 60 days, W-2 forms from the past two years, and tax returns if you are self-employed or freelance.
- Asset Verification: Recent bank statements from your checking and savings accounts to prove you have funds for a down payment or reserves.
- Existing Debt Details: Statements for current mortgages, car loans, student loans, or personal loans.
Having these documents neatly organized in a digital folder shows the lender that you are financially responsible and ready to handle a loan responsibly. It also speeds up underwriting, allowing you to get your funds much faster.
4. Choose the Right Type of Loan for Your Needs
Not all loans are created equal, and applying for the wrong type of loan can lead to unnecessary rejections. Before submitting an application, take time to understand the differences between various loan products and choose the one that matches your financial situation and goals.
The two main categories are secured loans and unsecured loans:
- Secured Loans: These require collateral—an asset like a car or a house—that the lender can take if you fail to repay the loan. Because the lender takes on less risk, secured loans often come with higher approval rates and lower interest rates. Examples include auto loans and mortgages.
- Unsecured Loans: These do not require collateral. Instead, approval is based entirely on your creditworthiness, income, and financial history. Because they carry more risk for the lender, they typically feature stricter approval criteria and sometimes higher interest rates. Examples include personal loans and standard credit cards.
Furthermore, consider where you are applying. Traditional big banks, local credit unions, and online peer-to-peer lenders all have different criteria. Credit unions, for instance, are member-owned and often offer more flexible terms and lower interest rates for people with average credit scores compared to massive national banks.
5. Save for a Healthy Down Payment or Reserve Funds
If you are applying for a loan that requires a down payment—such as a mortgage or an auto loan—putting down more money upfront can drastically improve your approval odds. A larger down payment reduces the overall loan amount the lender has to risk, which makes your application look much safer on paper.
For a mortgage, putting down 20 percent or more often eliminates the need to pay for Private Mortgage Insurance (PMI), which saves you money every single month and lowers your DTI ratio. For auto loans, a down payment of 10 to 20 percent can help protect you from being “upside down” on your loan—a situation where you owe more on the car than it is actually worth.
Even for unsecured personal loans where no down payment is required, having a healthy savings account buffer can work in your favor. Some lenders ask for proof of emergency savings during the underwriting process to ensure you can survive a temporary job loss or financial hiccup without defaulting on your new loan.
6. Avoid Common Mistakes That Lead to Instant Rejection
Many loan applicants accidentally sabotage their own chances right before or during the application process. Knowing what not to do is just as important as knowing what steps to take.
First, never apply for new credit right before applying for a major loan. Every time you apply for a new credit card, store card, or another loan, the lender performs a “hard inquiry” on your credit report. Multiple hard inquiries in a short period can lower your credit score and signal to lenders that you are desperate for cash.
Second, do not change jobs or career paths right before applying. Lenders love stability. They prefer borrowers who have steady, predictable employment for at least two years in the same industry. While changing jobs for a massive pay increase can be great, doing so right before applying for a mortgage or large personal loan can complicate the verification process.
Finally, do not make large, unexplained cash deposits or withdrawals in your bank accounts. Underwriters scrutinize bank statements closely. If they see large, mysterious sums moving in and out of your account right before approval, they may require extensive documentation to verify the source of the funds to comply with anti-money laundering regulations, which can stall your loan indefinitely.
Conclusion
Improving your chances of getting a loan is not about finding a magic loophole or tricking a financial system. It is about presenting yourself as a reliable, low-risk borrower who is well-prepared to handle debt responsibly.
By checking your credit score early, keeping your debt-to-income ratio low, organizing your documents, and avoiding common financial pitfalls, you take complete control of your financial narrative. Take these steps today, prepare your strategy carefully, and approach the lending market with confidence. When you are financially prepared, approval is much closer than you think.