Investing for Beginners: A Step-by-Step Guide

Taking control of your personal finances is one of the most impactful decisions you can make for your long-term independence. For many beginners, entering the world of investing feels overwhelming. Between complex jargon, endless financial news, and thousands of available assets, knowing where to begin can seem like a daunting task. However, building wealth through the market does not require a degree in finance or extraordinary mathematical skills. It simply requires a clear strategy, discipline, and a fundamental understanding of how money works over time.
At its core, investing is the process of putting your money to work so that it generates returns and grows faster than inflation. When you leave all your savings in a traditional bank account, the purchasing power of your money steadily declines over time due to rising living costs. By deploying capital into productive assets—such as equities, fixed-income instruments, or diversified funds—you allow compounding interest to multiply your wealth across decades.
This comprehensive guide walks you through every essential step necessary to launch a successful investment journey. You will learn how to evaluate your current financial foundation, understand the core asset classes available today, construct a resilient portfolio tailored to your goals, and manage risk like an experienced investor. By following these structured principles, you can transform uncertainty into confidence and start building sustainable financial security today.
Establishing Your Financial Foundation Before Buying Your First Asset
Before allocating a single dollar to the financial markets, you must ensure that your personal finances are stable and resilient. Jumping directly into market investments without proper preparation is similar to constructing a house on a weak foundation. Financial markets fluctuate, and unexpected life events can easily disrupt your strategy if you lack a protective safety net.
The very first milestone in your investment readiness is eliminating high-interest debt. Unsecured consumer debt, such as credit card balances and high-rate personal loans, often carries interest rates ranging from 15% to 30% annually. Because average historical stock market returns sit around 8% to 10% per year, paying off a high-interest debt provides a guaranteed return that no market investment can reliably beat. Clearing these liabilities immediately releases monthly cash flow and eliminates financial stress.
The second imperative milestone is establishing a robust emergency fund. An emergency fund is a dedicated pool of liquid cash designed exclusively to cover unexpected living costs, such as medical bills, urgent home repairs, or sudden job loss. Financial experts recommend storing between three and six months of essential living expenses in a high-yield savings account or a low-risk, highly liquid instrument. Having this buffer guarantees that you will never be forced to sell your long-term investments during a market downturn just to cover short-term personal expenses.
Finally, clear budgeting habits are required to sustain your investment program over time. Tracking your monthly income against mandatory expenses allows you to identify a consistent surplus. Investing is not a one-time event; it is a regular, disciplined habit. Establishing a fixed monthly contribution amount ensures steady accumulation over time, regardless of short-term market noise.
Understanding Core Investment Concepts: Risk, Return, and Liquidity
To make informed investment choices, you must understand the primary mechanics that govern every financial security. Every asset on the market operates along three fundamental dimensions: risk, potential return, and liquidity. Balancing these elements according to your personal circumstances is the key to long-term success.
The relationship between risk and return is direct and inescapable. High potential returns are always accompanied by higher risk, meaning a greater probability of short-term price volatility or permanent capital loss. Conversely, low-risk investments offer stable, predictable outcomes but yield lower returns. Beginners often make the mistake of chasing high yields without accounting for the underlying risks. Recognizing that higher potential gain requires accepting higher price fluctuations is essential for maintaining emotional stability during market drops.
Liquidity refers to how quickly and easily an asset can be converted into cash without losing significant value. Cash in a bank account is perfectly liquid. Real estate, on the other hand, is illiquid, as selling a property can take months and involves substantial transaction fees. Stock market equities and broad funds sit in the middle; they offer high liquidity because they can be sold instantly during market trading hours, though selling during a temporary dip may lock in a loss.
Another crucial concept every investor must master is the power of compounding. Compounding occurs when your investment returns begin generating their own earnings. Over short timeframes, compounding appears slow and unimpressive. However, over 10, 20, or 30 years, exponential growth takes over. The primary variable in maximizing compound interest is time. Starting early, even with modest amounts, is far more powerful than waiting to invest larger sums later in life.
Exploring Popular Asset Classes for Beginner Investors
The financial marketplace contains a broad range of investment vehicles, each serving distinct roles within a balanced portfolio. Broadly speaking, these instruments fall into two major categories: growth-oriented assets and capital-preservation assets.
Equities, commonly known as stocks, represent fractional ownership in a publicly traded corporation. When you purchase a share of stock, you become a part-owner of that business. If the business grows profits and expands, the value of your share increases, and the company may distribute a portion of profits directly to you as cash dividends. Equities offer strong long-term growth potential, but their market prices fluctuate daily based on economic conditions, company performance, and market sentiment.
Fixed-income securities, widely known as bonds, act as loans made by an investor to a borrower, such as a corporation or government entity. In exchange for your capital, the issuer pays periodic interest payments over a fixed term and returns the principal balance upon maturity. Government bonds issued by stable economies are considered among the safest investments available, offering predictable income and portfolio stabilization during equity declines, though their growth potential is limited.
Mutual funds and Exchange-Traded Funds (ETFs) are collective investment schemes that pool capital from thousands of individual investors to purchase a diversified basket of stocks, bonds, or other securities. Instead of selecting individual stocks, an investor can buy a single share of an ETF to instantly gain exposure to hundreds of top corporations globally. Index funds, a specific type of ETF or mutual fund designed to track broad market indices, feature exceptionally low management fees and consistently outperform most actively managed portfolios over long horizons.
Real estate offers another asset avenue, providing exposure to tangible property values and rental income streams. While direct property ownership requires substantial capital and active management, real estate investment vehicles enable individual investors to participate in commercial and residential property markets with modest capital and complete liquidity.
Determining Your Investor Profile and Risk Tolerance
Every individual approaches investing from a unique personal and financial situation. Designing an effective portfolio requires an honest evaluation of your personal risk tolerance, financial timeline, and ultimate wealth objectives.
Risk tolerance measures your emotional and psychological ability to endure portfolio declines without panicking. Some individuals remain calm when their account balance drops temporarily during a market pull-back, viewing it as a normal market cycle. Others experience intense anxiety and are tempted to liquidate their holdings to prevent further losses. Understanding your emotional limits prevents you from taking on excessive risk that could lead to panic selling at market bottoms.
Your time horizon—the amount of time between today and when you need to withdraw your funds—is equally decisive. Investors with multi-decade horizons, such as young professionals planning for retirement, can afford to take on higher allocations in equities. Over long periods, historical markets have reliably recovered from short-term downturns, giving long-term investors time to absorb fluctuations. Conversely, individuals nearing a specific goal in the next two to three years must prioritize capital preservation over aggressive growth, relying heavily on fixed income and cash equivalents.
Combining your risk tolerance, time horizon, and goals allows you to classify your investor profile into one of three general categories:
- Conservative Profile: Prioritizes wealth preservation and capital safety above high returns. Characterized by high exposure to fixed income, short-term debt instruments, and cash, with minimal stock exposure.
- Moderate Profile: Seeks a balance between capital growth and downside protection. Maintains a balanced mix of equities for long-term appreciation and bonds to smooth out market volatility.
- Aggressive Profile: Focuses maximum efforts on long-term capital appreciation, accepting substantial short-term price drops in exchange for higher potential compounding over time. Primarily composed of equities and growth funds.
Step-by-Step Guide to Opening an Account and Purchasing Your First Asset
Once you have defined your strategy and evaluated your financial position, you are ready to execute your investment plan. Transitioning from theory to action involves a straightforward, practical process.
Step 1: Select a Reliable Financial Institution or Brokerage
Choose an established, regulatory-compliant financial brokerage or platform. Compare institutions based on trading fee structures, account maintenance charges, customer service quality, administrative ease, and the clarity of their educational resources. Look for platforms that offer zero-commission trading on index funds and ETFs, user-friendly digital interfaces, and robust security protocols.
Step 2: Complete the Registration and Verification Process
Open your investment account by submitting required personal details, proof of identity, and tax identification information. Regulatory compliance standards require financial platforms to verify investor identities to secure transactions and prevent financial fraud. During setup, you will complete a suitability questionnaire that helps the platform confirm your risk profile.
Step 3: Transfer Capital into Your Investment Account
Link your primary checking or savings account to your new brokerage profile. Initiate an initial electronic transfer of funds. It is best practice to begin with an amount you feel comfortable allocating to long-term assets without compromising your monthly living expenses.
Step 4: Select Your Primary Assets
For absolute beginners, simplicity is the ultimate sophistication. Rather than trying to pick individual winning stocks—a strategy that frequently underperforms broad market benchmarks—focus on broad-market index ETFs. A combination of a total international equity fund and a broad total bond market fund provides global diversification through a minimal number of holdings.
Step 5: Execute Your Purchase Order
Navigate to the trading interface, input the ticker symbol of your chosen ETF or fund, and select your preferred order type. A market order executes the trade immediately at the current prevailing market price, while a limit order executes only when the asset hits a specific price you set. For standard long-term index purchasing, market orders during standard operating hours are efficient and practical.
The Power of Diversification: Protecting Your Portfolio From Volatility
One of the most essential principles in modern portfolio management is diversification. Diversification is the technique of spreading your capital across various asset classes, industries, geographic regions, and company sizes to minimize risk.
The core objective of diversification is simple: prevent the poor performance of a single company or economic sector from severely damaging your overall wealth. If you invest your entire savings into a single company’s stock, your financial future is tied exclusively to that business’s management decisions, competitive pressures, and industry health. If that company faces bankruptcy, you risk losing your total investment.
When you diversify across hundreds of corporations across different sectors—such as technology, healthcare, consumer goods, energy, and financial services—the underperformance of a few companies is offset by the growth of others. Furthermore, holding assets that react differently to economic conditions, like pairing equities with government bonds, creates smoother portfolio performance over time.
Effective diversification includes several distinct layers:
- Asset Class Diversification: Combining stocks, bonds, real estate, and liquid cash.
- Sector Diversification: Spreading equity holdings across technology, industrial, healthcare, utilities, and consumer goods markets.
- Geographic Diversification: Allocating capital internationally to prevent exposure to a single national economy or currency fluctuation.
- Company Size Diversification: Holding a mix of large-capitalization market leaders, mid-sized growth firms, and small-capitalization companies.
Dollar-Cost Averaging: The Ultimate Strategy for Long-Term Consistency
One of the largest hurdles new investors face is the psychological anxiety of market timing. Beginners often worry about buying at the peak of a market cycle right before a major price drop. Attempting to time the market—predicting exact price tops and bottoms—is virtually impossible, even for professional fund managers.
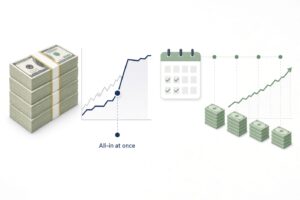
Dollar-Cost Averaging (DCA) is an elegant, battle-tested strategy that completely removes emotional timing from the investment equation. Under a dollar-cost averaging plan, you invest a fixed amount of money at regular intervals—such as monthly or bi-weekly—regardless of market conditions or current asset prices.
When market prices are high, your fixed cash contribution automatically buys fewer shares. When market prices fall during a temporary downturn, your same fixed cash contribution automatically buys a larger quantity of shares. Over time, this disciplined routine lowers your average purchase price per share and eliminates the emotional temptation to panic during market corrections or buy recklessly during market bubbles.
Automating your investments through recurring monthly bank transfers makes dollar-cost averaging seamless. By turning wealth building into an automated routine, you build portfolio value consistently without needing to monitor daily market movements or headline news.
Common Mistakes Beginner Investors Must Avoid
Achieving long-term investment success depends as much on avoiding costly errors as it does on making good choices. New investors frequently encounter predictable psychological traps and strategic mistakes that can erode their hard-earned capital.
1. Chasing Short-Term Speculation and Market Trends
Novice investors are often drawn to trendy speculative assets promising rapid riches. Speculation is not investing. Real investing relies on underlying economic productivity, cash flow generation, and disciplined long-term asset growth. Chasing hype usually results in buying assets at inflated tops right before a sharp collapse.
2. Emotional Decision-Making and Panic Selling
Financial markets naturally move in cycles, experiencing periodic pullbacks, corrections, and temporary bear markets. Panic selling occurs when investors let fear take over during a price drop, converting temporary paper losses into permanent financial losses. Successful investors maintain perspective, recognizing that market pullbacks offer opportunities to acquire quality assets at discounted prices.
3. Portfolio Over-Complication
Many beginners believe that a good portfolio requires owning dozens of individual stocks, complex derivatives, and esoteric products. Over-complicating your strategy increases management hassle, transaction fees, and tax reporting obligations. A simple portfolio composed of a few broad-market index funds routinely outperforms complex, overly active trading strategies over multi-year periods.
4. Neglecting Investment Fees and Operational Costs
Expense ratios, management fees, and account maintenance charges may seem small as percentages, but over decades, high fees significantly drain compound interest. Always choose low-cost index funds with minimal expense ratios to ensure the vast majority of market returns remain in your account.
5. Lacking Patience and Discipline
Wealth accumulation through regular investing is a slow, methodical journey. Expecting overnight results leads to frustration and unnecessary risk-taking. Patience, consistency, and a multi-year horizon remain the most effective drivers of compounding returns.
Maintaining and Rebalancing Your Investment Portfolio
While a simple index-focused portfolio requires very little daily attention, it is not entirely hands-off over time. As market conditions evolve, asset values shift at different rates, gradually altering your original portfolio balance.
For example, suppose you initially design a portfolio consisting of 80% equities and 20% bonds. Following a strong multi-year stock market rally, the value of your equities may grow faster than your bond holdings, pushing your asset allocation to 90% equities and 10% bonds. This shift unintentionally exposes your overall portfolio to higher volatility than your original plan intended.
Portfolio rebalancing is the periodic process of adjusting your asset allocations back to their target proportions. Rebalancing can be accomplished in two primary ways:
- Sales-Based Rebalancing: Selling off a small portion of the overperforming asset class and using the proceeds to purchase underperforming asset classes.
- Contribution-Based Rebalancing: Directing new monthly investment capital exclusively into the underperforming asset classes until the target balance is naturally restored.
For most individual investors, conducting a portfolio review once or twice a year is sufficient. Contribution-based rebalancing is often ideal for growing accounts, as it avoids triggering taxable capital gains events caused by selling appreciated assets.
Taking Action on Your Wealth Journey
Investing is not a privilege reserved exclusively for high-net-worth individuals; it is a vital tool accessible to anyone seeking long-term financial stability. The path to financial growth does not require predicting market movements or mastering complex trading algorithms. Instead, it relies on clear fundamentals: establishing an emergency fund, clearing high-interest obligations, maintaining a diversified core portfolio, and contributing capital regularly regardless of short-term volatility.
The single most powerful advantage an investor possesses is time. Every year spent waiting on the sidelines reduces the power of compound interest. By applying the step-by-step principles outlined in this guide—staying disciplined, keeping expenses low, and focusing on long-term strategy—you can navigate the financial markets with confidence and build lasting security for your future.