How to Prepare Your Finances Before Taking Out a Loan

Taking out a loan is a major financial decision. Whether you are buying a car, consolidating debt, funding home improvements, or handling an unexpected emergency, borrowing money impacts your monthly budget and your long-term financial health.
Many people rush into the loan application process only to face high interest rates, unfavorable terms, or even outright rejection. Proper preparation makes all the difference. When you take the time to evaluate your financial standing, clean up your credit, and build a solid repayment strategy, lenders view you as a reliable borrower. This preparation unlocks lower interest rates, better loan terms, and greater peace of mind.
This comprehensive guide covers everything you need to know to prepare your finances effectively before signing any loan agreement.
1. Define Your Purpose and Calculate the Exact Amount Needed
Before looking at lenders or comparing interest rates, you must clearly understand why you are borrowing money and how much you actually need. Vague borrowing leads to over-borrowing, which results in paying unnecessary interest on funds you do not use.
Separate Needs from Wants
Ask yourself whether the loan fulfills an essential financial need or a discretionary want. Loans used for wealth-building assets, essential education, or debt consolidation with lower interest rates often make strategic sense. Loans used for lifestyle expenses or depreciating luxury items can trap you in expensive debt cycles.
Calculate the Precise Cost
Do not guess how much money you need. If you are buying a home or car, get estimates or quotes. If you are consolidating debt, list every single balance, interest rate, and minimum payment to determine the exact total.
- Principal Amount: The exact cost of the project, purchase, or debt payoff.
- Associated Fees: Factor in origination fees, closing costs, application fees, or prepayment penalties.
- Buffer for Unexpected Costs: Add a small cushion for price fluctuations, especially for home improvement or medical expenses.
2. Assess Your Current Financial Health
Lenders evaluate your financial health before approving a loan. You should do the exact same thing beforehand to avoid unpleasant surprises.
Review Your Income and Cash Flow
Examine your monthly take-home pay and compare it against your regular living expenses. Use recent bank statements and pay stubs to get an accurate average. If your income fluctuates, use your lowest earning month as a baseline for safety.
Calculate Your Debt-to-Income (DTI) Ratio
Your Debt-to-Income (DTI) ratio is one of the most critical metrics lenders use to determine your borrowing capacity. It measures the percentage of your monthly gross income that goes toward paying debts.
To calculate your DTI:
- Add up all your monthly debt payments (rent/mortgage, credit card minimums, student loans, car payments).
- Divide that total by your gross monthly income (income before taxes).
- Multiply by 100 to get a percentage.
- Under 36%: Generally considered a healthy DTI ratio, showing lenders you manage debt well.
- 36% to 49%: Often acceptable depending on the lender and loan type, but may result in higher interest rates.
- 50% and Above: Indicates high financial strain. Lenders may view you as high risk, leading to loan denials.
If your DTI is too high, focus on paying down existing revolving debts or increasing your income before applying for a new loan.
3. Check and Improve Your Credit Score
Your credit score is your financial resume. It tells lenders how responsibly you have managed credit in the past. A high credit score opens doors to the lowest interest rates, saving you thousands of dollars over the life of a loan.
Obtain Your Credit Report
You are entitled to a free copy of your credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) annually through official channels. Review your report carefully for errors, such as accounts you do not recognize, incorrect late payments, or outdated information. Dispute any errors immediately.
Key Factors That Influence Your Score
- Payment History (35%): Making on-time payments is the single most important factor. Even one late payment can drag down your score.
- Credit Utilization (30%): This measures how much revolving credit you are using compared to your total limit. Try to keep your credit card balances below 30% of your limit—ideally below 10%.
- Length of Credit History (15%): Older accounts help your score. Avoid closing old credit cards unless they carry high annual fees.
- Credit Mix (10%): Having a healthy mix of installment loans (like car loans or mortgages) and revolving credit (like credit cards) benefits your score.
- New Credit (10%): Opening multiple new credit accounts in a short period signals financial distress to lenders.
Steps to Boost Your Score Before Applying
- Pay down outstanding credit card balances to lower your credit utilization ratio.
- Automate your monthly bills to ensure you never miss a payment deadline.
- Keep old accounts open to maintain a long credit history.
- Avoid applying for new credit cards or loans in the months leading up to your major loan application.
4. Build an Emergency Fund as a Safety Net
Life is unpredictable. Job loss, medical emergencies, or urgent car repairs can happen at any time. Taking out a loan without an emergency fund leaves you vulnerable to defaulting if unexpected expenses arise.
Why Savings Matter to Lenders
While some unsecured personal loans do not require collateral, lenders want to see that you have a financial cushion. Savings prove that a minor financial hiccup will not instantly cause you to miss a loan payment.
How Much Should You Save?
Aim to build an emergency fund covering at least three to six months of essential living expenses. If your income is irregular or your job security fluctuates, lean toward six to nine months. Keep this money in a liquid, easily accessible high-yield savings account where it earns interest while remaining safe.
5. Craft a Realistic Repayment Plan
Too many borrowers focus entirely on getting approved, neglecting how they will handle the monthly payments. Before you apply, integrate the anticipated loan payment into your monthly household budget.
Use a Loan Calculator
Run the numbers using online loan calculators. Test different loan terms to see how they impact your monthly budget:
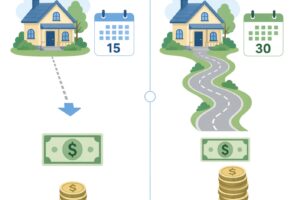
- Short-Term Loans (e.g., 2 or 3 years): Feature higher monthly payments but lower overall interest costs.
- Long-Term Loans (e.g., 5 or 7 years): Feature lower, more manageable monthly payments, but you will pay significantly more interest over time.
Stress-Test Your Budget
Ask yourself what would happen if your income dropped temporarily or expenses rose. Can your monthly budget absorb the loan payment without forcing you to miss rent, skip meals, or rely on high-interest credit cards? If the payment leaves zero room for error, consider a smaller loan amount or wait until your financial position strengthens.
6. Shop Around and Compare Lenders
Never accept the first loan offer you receive. Different lenders—including traditional banks, credit unions, and reputable online platforms—offer vastly different interest rates, fee structures, and repayment terms.
Get Pre-Qualified
Many lenders allow you to check your potential rates and terms through a soft credit check, which does not impact your credit score. Use pre-qualification tools to shop around and compare offers from at least three different financial institutions.
Compare More Than Just the Interest Rate
While the Annual Percentage Rate (APR) is crucial, examine all components of the loan offer:
- APR (Annual Percentage Rate): Represents the true yearly cost of the loan, including interest and mandatory fees.
- Origination Fees: Upfront fees charged by lenders to process the loan, often deducted directly from your disbursed funds.
- Prepayment Penalties: Fees charged if you pay off your loan early. Avoid lenders that penalize you for early repayment.
- Customer Service and Reviews: Research the lender’s reputation, mobile app functionality, and customer support responsiveness.
Preparing your finances before taking out a loan is the ultimate key to borrowing smart. By defining your exact financial needs, assessing your DTI ratio, cleaning up your credit score, establishing an emergency fund, planning your budget, and shopping around for the best rates, you put yourself firmly in the driver’s seat.
Taking these proactive steps protects you from predatory interest rates, prevents debt traps, and ensures that the loan you take out serves as a powerful stepping stone toward your financial goals rather than a burden. Take your time, do the math, and borrow with confidence.