What Are the Different Types of Loans?

Managing your personal finances can sometimes feel like navigating a complex maze, especially when an unexpected expense arises or a major life goal comes into view. Whether you are dreaming of owning your first home, looking to consolidate high-interest credit card debt, or needing funds to cover sudden medical bills, understanding the mechanics of borrowing is essential. Loans act as powerful financial tools that, when used wisely, can help bridge the gap between your current financial capacity and your long-term objectives.
However, diving into the borrowing world without a clear roadmap can lead to confusion, high interest rates, and unnecessary financial stress. Lenders offer a vast array of financial products tailored to specific needs, credit profiles, and financial situations. Knowing the distinction between secured and unsecured loans, installment lines and revolving credit, and specialized financing options empowers you to make informed decisions that protect your financial health.
This comprehensive guide breaks down everything you need to know about the different types of loans available today. By exploring how these financial products work, their benefits, and their potential drawbacks, you will be well-equipped to choose the right borrowing strategy for your unique circumstances.
Understanding the Basics: How Loans Work
Before exploring specific loan categories, it is vital to understand the foundational mechanics of borrowing money. At its core, a loan is a financial agreement between a borrower and a lender—such as a bank, credit union, or online lending platform. Under this agreement, the lender provides a specified sum of money, which the borrower agrees to repay over a predetermined period, typically with added interest and fees.
Interest acts as the cost of borrowing. It is calculated as a percentage of the principal amount—the initial sum borrowed—and is paid to the lender periodically, usually monthly. The interest rate you receive depends heavily on several factors, including your credit score, income, debt-to-income ratio, and economic conditions. A higher credit score generally signals lower risk to lenders, resulting in lower interest rates and more favorable loan terms.
Loans generally fall into two primary structural categories:
- Installment Loans: These provide a lump sum of money upfront, which is repaid through fixed, scheduled monthly payments over a set term (e.g., three, five, or thirty years). Once the balance is fully paid, the account closes.
- Revolving Credit: This functions as an ongoing line of credit where you can borrow up to a specific credit limit, repay what you use, and borrow again as needed. Credit cards and home equity lines of credit (HELOCs) are classic examples.
Secured Versus Unsecured Loans
One of the most critical distinctions in the lending landscape involves how loans are backed. Lenders assess risk in various ways, and the presence or absence of collateral significantly shapes the borrowing experience.
Secured Loans
Secured loans require the borrower to pledge an asset—known as collateral—to back the financing. Common examples of collateral include residential real estate, automobiles, savings accounts, or valuable investments. If the borrower fails to make payments and defaults on the agreement, the lender holds the legal right to seize the collateral to recover their losses.
Because the lender assumes less risk, secured loans often feature higher borrowing limits, longer repayment terms, and substantially lower interest rates compared to their unsecured counterparts. Common examples include mortgages and auto loans.
Unsecured Loans
Unsecured loans do not require any collateral. Instead of seizing assets in the event of a default, lenders rely entirely on the borrower’s creditworthiness, financial history, and promise to repay. Because the lender takes on a much higher level of risk, unsecured loans typically feature stricter approval requirements, lower borrowing limits, and higher interest rates. Personal loans and credit cards are the most common forms of unsecured credit.
Personal Loans: Flexible Financing for Everyday Needs
Personal loans represent one of the most versatile borrowing options available to consumers. Typically structured as unsecured installment loans, personal loans provide borrowers with a lump sum of cash that can be used for a wide variety of purposes. Lenders rarely restrict how you use the funds, making them a popular choice for managing life’s unpredictable moments.
Common Uses for Personal Loans
- Debt Consolidation: Combining multiple high-interest debts, such as credit card balances, into a single monthly payment with a lower fixed interest rate.
- Home Improvements: Funding renovations, repairs, or upgrades that enhance living comfort and property value without tapping into home equity.
- Major Life Events: Covering the costs of weddings, milestone celebrations, or unexpected travel emergencies.
- Medical Expenses: Paying for out-of-pocket medical procedures, dental care, or veterinary bills not fully covered by insurance.
Key Considerations
While personal loans offer incredible flexibility, borrowers must carefully evaluate the associated costs. Origination fees, which are deducted upfront by some lenders, can reduce the total cash amount you receive. Furthermore, opting for a longer repayment term lowers monthly payments but increases the total amount of interest paid over the life of the loan.
Mortgages: Financing Your Dream Home
For the vast majority of individuals, purchasing real estate requires external financing. A mortgage is a specialized type of secured loan used specifically to buy homes, land, or other real property. In this arrangement, the purchased property serves as the collateral. If the borrower stops making payments, the lender can initiate foreclosure proceedings to reclaim the property.
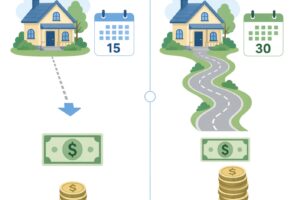
Mortgages are unique due to their long lifespans—typically lasting fifteen or thirty years—and involve complex structures that require careful analysis.
Major Mortgage Varieties
- Fixed-Rate Mortgages: The interest rate remains constant throughout the entire life of the loan, ensuring that your monthly principal and interest payments never change. This stability makes budgeting significantly easier.
- Adjustable-Rate Mortgages (ARMs): The interest rate remains fixed for an initial period (such as five, seven, or ten years) and then fluctuates periodically based on broader market indexes. ARMs often start with lower initial rates than fixed-rate options but carry the risk of higher payments later.
- Government-Backed Mortgages: Programs insured or guaranteed by federal agencies—such as FHA loans, VA loans (for military members and veterans), and USDA loans (for rural housing)—help expand homeownership by offering lower down payment requirements and flexible credit guidelines.
Auto Loans: Getting You on the Road
Vehicles are essential tools for commuting, running errands, and maintaining independence, yet buying a car outright with cash is out of reach for many shoppers. Auto loans are secured installment loans specifically designed to finance the purchase of a new or used car, truck, or SUV.
The vehicle being purchased serves directly as the collateral for the financing. If payments lapse, the lender can repossess the car. Because the asset depreciates rapidly—losing value the moment it drives off the dealer’s lot—auto loan terms are generally shorter than mortgages, commonly ranging from 36 to 72 months.
Financing Options
Borrowers can secure auto financing through multiple avenues:
- Dealership Financing: Conveniently arranged at the point of sale, though shoppers should compare rates to ensure they are getting a competitive deal.
- Banks and Credit Unions: Securing pre-approval from a financial institution before shopping gives buyers strong negotiating power and transparent terms.
- Online Lenders: Digital platforms offer quick comparisons across multiple lenders, helping borrowers find low rates tailored to their credit profiles.
Student Loans: Investing in Higher Education
Education is one of the most impactful investments an individual can make in their future earning potential. However, rising tuition costs mean that many students rely on student loans to cover undergraduate, graduate, or professional programs.
Student loans are unique because the “asset” being financed is the borrower’s future earning capacity rather than physical property. They are categorized into two primary types:
Federal Student Loans
Funded by the federal government, these loans generally offer fixed interest rates, income-driven repayment plans, and options for deferment or forbearance during periods of financial hardship. They typically do not require a credit check or a co-signer, making them accessible to young adults with limited credit histories.
Private Student Loans
Issued by banks, credit unions, or online lenders, private student loans fill the funding gap when federal aid and scholarships are insufficient. These loans rely heavily on the credit score and income of the borrower—often requiring a creditworthy co-signer—and feature variable or fixed interest rates based on market conditions.
Business Loans: Fueling Entrepreneurship and Growth
Entrepreneurs and business owners frequently require external capital to launch a new venture, manage cash flow fluctuations, purchase inventory, or expand operations. Business loans are commercial financing products tailored to the unique demands of running a enterprise.
Lenders evaluate business plans, annual revenue, cash flow statements, and personal credit histories when underwriting these loans. Depending on the business model and objective, owners can choose from several options:
- Term Loans: Traditional lump-sum financing repaid over a set period for major investments like equipment or real estate.
- Small Business Administration (SBA) Loans: Government-backed loans offering favorable terms and lower down payments for qualifying small businesses.
- Business Lines of Credit: Flexible, revolving funding sources that allow companies to draw cash as needed to manage seasonal cash flow gaps.
- Equipment Financing: Secured loans specifically designed to purchase machinery, computers, or commercial vehicles, where the equipment itself acts as collateral.
Debt Consolidation Loans: Streamlining Your Finances
Managing multiple debt payments across different credit cards, medical bills, and personal loans each month can quickly become overwhelming, leading to missed due dates and costly late fees. A debt consolidation loan is a specialized personal loan used to pay off all smaller, scattered debts, leaving the borrower with just one streamlined monthly payment.
Benefits of Debt Consolidation
- Simplified Budgeting: Tracking a single monthly payment is significantly easier than managing five or ten distinct bills.
- Lower Interest Rates: Securing a consolidation loan with a lower interest rate than your existing credit cards reduces the overall cost of borrowing.
- Fixed Payoff Timeline: Unlike revolving credit, which can linger indefinitely with minimum payments, installment consolidation loans provide a definitive end date for becoming debt-free.
Comparing Loan Types at a Glance
To help you quickly evaluate which financing category aligns with your current goals, review the following comparison table highlighting key structural differences:
| Loan Category | Primary Purpose | Secured or Unsecured? | Typical Term Length | Common Risk Factors |
| Personal Loans | Versatile (debt consolidation, emergencies) | Usually Unsecured | 1 to 7 years | Higher interest rates for fair/poor credit |
| Mortgages | Purchasing real estate or land | Secured (Property) | 15 or 30 years | Risk of foreclosure if payments fail |
| Auto Loans | Buying cars, trucks, or motorcycles | Secured (Vehicle) | 3 to 6 years | Rapid vehicle depreciation |
| Student Loans | Funding higher education | Both Available | 10 to 20+ years | Long-term debt obligations |
| Business Loans | Commercial growth and operations | Both Available | Varies widely | Strict qualification and revenue criteria |
Factors to Consider Before Applying for Any Loan
Taking on debt is a major financial commitment that requires careful forethought and strategic planning. Before submitting an application with any lender, ask yourself the following critical questions to protect your financial stability:
1. Can You Afford the Monthly Payment?
Review your monthly budget meticulously. Ensure that the new loan payment fits comfortably alongside your existing essential expenses, savings contributions, and living costs without straining your finances.
2. What Is the Total Cost of Borrowing?
Do not focus solely on the monthly payment amount. Examine the annual percentage rate (APR), origination fees, closing costs, and prepayment penalties. Calculate the total cumulative amount you will pay over the entire life of the loan.
3. How Does Your Credit Score Look?
Your credit score dictates the interest rates you will be offered. Taking time to review your credit report, correct errors, and pay down existing balances before applying can save you thousands of dollars in interest charges.
4. Have You Shopped Around?
Loan terms, fees, and interest rates vary drastically between financial institutions. Always request quotes from multiple lenders—including traditional banks, credit unions, and reputable online platforms—to secure the most competitive offer available.
Making Informed Borrowing Decisions
Navigating the financial landscape becomes significantly less daunting when you understand the mechanics and purposes of different loan types. Whether you are pursuing homeownership, consolidating debt, funding your education, or expanding a business, the right loan can serve as a valuable stepping stone toward your goals.
By carefully evaluating whether you need a secured or unsecured product, assessing your budget realistically, and shopping around for the best rates, you can borrow responsibly and protect your long-term financial health. Knowledge is your greatest asset when managing debt—use it wisely to build a secure and prosperous future.