NYSE vs. London Stock Exchange: What Investors Should Know

Navigating international capital markets requires a clear understanding of where global equity flows, how liquidity is distributed, and how market architecture impacts portfolio execution. The New York Stock Exchange (NYSE) and the London Stock Exchange (LSE) stand as two of the most prominent financial hubs in history. While both venues facilitate capital raising and secondary market trading, their structural dynamics, listed company profiles, regulatory frameworks, and operational schedules differ significantly.
For institutional allocation strategies and retail investment models alike, choosing between or balancing exposure across the NYSE and LSE involves evaluating total market capitalization, dividend taxation regimes, trading hours, liquidity depth, and sectoral concentration. This guide analyzes the core differences between these exchange powerhouses to help inform strategic investment decisions.
Market Capitalization and Overall Scale Dynamics
Scale and liquidity represent primary points of divergence when comparing North American and European financial centers. The New York Stock Exchange represents the largest stock exchange in the world by market capitalization. Hosting thousands of enterprise-scale corporations—including global mega-cap technology firms, industrial conglomerates, financial giants, and consumer staples—the NYSE acts as a primary benchmark for total global market sentiment.
In comparison, the London Stock Exchange operates as Europe’s premier international financing destination. While its total aggregate market capitalization is smaller than that of the NYSE, the LSE maintains a high concentration of multinational corporations, particularly across commodity, energy, banking, and pharmaceutical sectors.
- The NYSE Advantage: Deep capital pools, massive daily average trading volume, and unmatched market depth, providing tighter bid-ask spreads for major blue-chip equities.
- The LSE Advantage: High exposure to international revenue streams, strong cross-border listings, and significant representation in traditional high-dividend sectors.
For market participants, market capitalization translates directly into liquidity risk management. High-volume trading environments like the NYSE allow large position entry and exit with minimal price slippage. Conversely, the LSE offers focused access to global resource and defensive income stocks, making it an essential component for international diversification.
Regulatory Environment and Listing Frameworks
Regulatory standards govern how companies disclose financial health, report earnings, and manage corporate governance. These frameworks directly impact investor protection, reporting transparency, and market predictability.
The US Regulatory Standard: SEC and Sarbanes-Oxley
Companies listed on the NYSE operate under the jurisdiction of the United States Securities and Exchange Commission (SEC). US listing requirements enforce strict compliance mandates, such as the Sarbanes-Oxley Act (SOX), which demands stringent internal accounting controls, independent audit verification, and quarterly earnings disclosures via Form 10-Q and Form 10-K filings.
While these comprehensive reporting mandates increase operational compliance costs for issuer corporations, they offer investors a high degree of standardized financial transparency and rigorous fraud protection.
The UK Regulatory Standard: FCA and Listing Categories
The London Stock Exchange operates under the regulatory supervision of the Financial Conduct Authority (FCA). The LSE offers distinct trading tiers to accommodate various corporate maturity phases:
- Main Market (Premium Listing): Requires strict compliance with UK Corporate Governance Codes, offering high investor protection standards comparable to US markets.
- Main Market (Standard Listing): Provides a more flexible regulatory baseline aligned with EU and global harmonized standards.
- Alternative Investment Market (AIM): A sub-market designed specifically for high-growth, early-stage, and smaller-cap companies. AIM features streamlined regulatory burdens, allowing emerging businesses to raise capital efficiently.
Investors reviewing LSE assets must identify which market segment a security belongs to, as governance oversight and disclosure depth vary between AIM and Main Market listings.
Sector Weighting and Index Diversity Comparison
Sector concentration shapes portfolio exposure, risk volatility, and dividend yield profiles. The NYSE and LSE present distinct sector distributions reflecting their underlying regional economic foundations.
| Asset Characteristic | New York Stock Exchange (NYSE) | London Stock Exchange (LSE) |
|---|---|---|
| Primary Benchmarks | S&P 500, Dow Jones Industrial Average | FTSE 100, FTSE 250 |
| Dominant Sectors | Technology, Financials, Healthcare, Industrials | Energy, Mining, Financials, Consumer Staples |
| Growth vs. Value Profile | High allocation toward growth & large-cap innovation | Strong skew toward value, cyclical, & income assets |
| Dividend Yield Averages | Generally lower yield, higher capital appreciation focus | Historically higher average dividend yield metrics |
| Market Segments | Main Exchange | Main Market (Premium/Standard) & AIM |
The NYSE hosts major global market leaders across healthcare, industrial automation, technology, and consumer platforms. As a result, capital invested in NYSE-listed assets often seeks long-term equity growth, operational expansion, and innovation-driven returns.
Conversely, the LSE’s primary flagship index, the FTSE 100, features high weights in global banking groups, international oil majors, mining operators, and defensive consumer goods manufacturers. Consequently, investors seeking defensive equity plays, value investing strategies, and recurring dividend income frequently utilize the LSE to balance growth-heavy portfolios.
Trading Hours, Overlap, and Global Execution Strategies
Time zone alignment affects market liquidity, news response speed, and execution pricing. Understanding operating schedules enables traders to optimize execution timing, particularly during multi-market arbitrage opportunities or major economic data announcements.
London Stock Exchange Schedule
- Standard Trading Session: 08:00 to 16:30 Greenwich Mean Time (GMT).
- Operational Characteristics: Captures early morning liquidity across European markets, bridging trading activity between Asian market closes and North American openings.
New York Stock Exchange Schedule
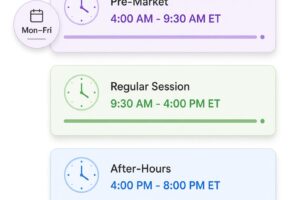
- Standard Trading Session: 09:30 to 16:00 Eastern Time (ET).
- Extended Hours: Pre-market and post-market electronic communication networks (ECNs) allow extended trading coverage.
The Transatlantic Overlap Period
A critical window for global capital markets occurs during the daily overlap period when both the NYSE and LSE are open simultaneously. This occurs during the morning trading hours in New York and late afternoon trading in London.
During this overlapping timeframe, liquidity reaches peak intraday levels across cross-listed equities, exchange-traded funds (ETFs), depositary receipts, and foreign exchange markets. Institutional execution strategies often target this period to execute large volume orders with lower bid-ask spreads and reduced volatility risk.
Dividend Taxation and Cross-Border Withholding Considerations
Cross-border tax treatment significantly influences net investment returns. Differences in international withholding taxes between the US and the UK require strategic structural planning.
US Dividend Withholding Structure
When foreign investors hold US equities listed on the NYSE, cash dividends are generally subject to a standard US federal withholding tax rate.
- Dependent on double-taxation treaties between the investor’s country of residence and the US, this tax rate is often reduced when proper tax documentation (such as Form W-8BEN) is filed.
- However, withholding tax directly reduces cash flow yield on dividend-focused portfolios.
UK Dividend Withholding Advantages
The UK taxation framework presents a distinct structural characteristic for foreign investors holding equities listed on the LSE:
- The UK does not levy a withholding tax on cash dividends paid by UK-incorporated companies to international shareholders (with limited exceptions regarding certain real estate investment trusts).
- This withholding tax policy makes UK equities listed on the LSE attractive for yield-focused portfolios seeking gross dividend collection without automated foreign tax deductions at the source.
Exchange-Traded Funds (ETFs) and Structural Investment Vehicles
Building diversified international exposure relies heavily on investment vehicle structure. Both markets support massive ETF ecosystems, but their regulatory structures differ.
US ETF Ecosystem (NYSE Arca)
The NYSE hosts an expansive ETF marketplace, characterized by high trading volume, tight spreads, and low management expense ratios. US-domiciled ETFs offer extensive options across single-country funds, sector baskets, thematic strategies, and fixed-income assets. However, non-US retail investors may face regulatory restrictions when purchasing US-domiciled ETFs directly due to local investor protection mandates.
UK and European ETF Ecosystem (UCITS on LSE)
The London Stock Exchange features a comprehensive selection of Undertakings for Collective Investment in Transferable Securities (UCITS) compliant ETFs.
- UCITS Compliance: UCITS-certified funds adhere to strict European risk diversification and investor protection standards, making them accessible to international investors worldwide.
- Currency Flexibility: LSE lists ETFs denominated in multiple currencies, including British Pounds (GBP), US Dollars (USD), Euros (EUR), and Japanese Yen (JPY). This multi-currency listing model allows investors to manage currency conversion risks without leaving the primary exchange ecosystem.
- Accumulation Share Classes: Many LSE-listed ETFs offer “accumulation” share classes that automatically reinvest dividend distributions internally. This structure enables capital compounding without triggering immediate tax events in certain jurisdictions.
Depository Receipts and Cross-Border Market Access
Investors often seek exposure to international corporations without maintaining foreign currency trading accounts on local exchanges. Both exchanges address this through depositary receipt mechanisms.
American Depositary Receipts (ADRs) on the NYSE
American Depositary Receipts allow non-US corporations to list their equity on US exchanges, denominated in US Dollars. Sponsored ADRs trade under the same operational clearing standards as domestic US equities, offering standard dividend distribution in US Dollars. This enables investors on the NYSE to gain exposure to foreign blue-chip companies while utilizing standard US execution infrastructure.
Global Depositary Receipts (GDRs) on the LSE
The London Stock Exchange serves as an international market for Global Depositary Receipts. The LSE International Order Book (IOB) allows investors to trade GDRs representing leading enterprise corporations from emerging and frontier markets. This provides efficient access to international growth markets through a single institutional platform with standardized settlement protocols.
Primary IPO Listings and Corporate Capital Raising Trends
Where companies choose to conduct an Initial Public Offering (IPO) reflects corporate liquidity preferences, valuation benchmarks, and capital availability.
- Valuation Premia in New York: Technology, biotechnology, and high-growth software enterprises historically seek primary listings on the NYSE (or NASDAQ) to capture higher valuation multiples and deeper institutional analyst coverage. The massive retail and institutional capital participation in the US market provides extensive secondary market liquidity.
- International Capital Focus in London: The LSE remains a primary capital hub for energy transformation projects, international mining consortia, global investment trusts, and cross-border holding companies. The LSE’s deep historical ties to international commodity markets continue to pull resource-focused issuers to its Main Market.
Recent regulatory reforms in the UK aim to streamline listing processes, modernize dual-class share structure rules, and enhance the competitiveness of the LSE for tech innovation listings, signaling continued structural evolution across transatlantic exchanges.
Strategic Portfolio Allocation: Choosing the Right Exchange
Determining whether to prioritize the NYSE or the LSE depends on portfolio objectives, risk tolerance, sector targets, and tax considerations.
Consider Prioritizing the NYSE If:
- Your Focus Is Growth: You prioritize allocation toward software innovation, artificial intelligence, medical technology, and high-growth consumer markets.
- Maximum Liquidity Is Required: You require maximum daily volume and minimal execution slippage across mega-cap asset classes.
- You Trade US Dollar Assets: You prefer direct settlement and income in USD without currency conversion fees across foreign markets.
Consider Prioritizing the LSE If:
- You Seek Income and Value: You aim to build an income-oriented portfolio focused on high-dividend energy, materials, consumer staples, and financial firms.
- Tax Efficiency Matters: You are an international investor seeking dividend income without foreign withholding tax deductions at the source.
- You Need UCITS ETF Access: You require UCITS-compliant index funds and multi-currency ETF structures tailored for global wealth management frameworks.
Rather than viewing the NYSE and LSE as mutually exclusive options, sophisticated global allocation models often utilize both exchanges. Combining the growth orientation and liquidity of the NYSE with the defensive income characteristics and tax-efficient structures of the LSE creates a balanced, internationally resilient equity foundation.